Tooling is the line on a custom cable quotation that generates the most correspondence and the least clarity. A buyer sees a four-figure charge for something they will never receive as a physical object, or alternatively sees no charge at all and suspects the cost has been hidden in the unit price. Both arrangements are legitimate. What causes trouble is not which one is chosen but whether the terms around it were written down before work started.
The three questions that decide every dispute are simple: who owns the tool, what happens to the charge if the program reaches its committed volume, and what happens if the program stops early. Answer those three in the purchase order and the tooling line stops being a source of friction.
Why Tooling Is Charged Separately at All
A mold, a crimping die set, a test fixture and a bespoke stripping blade are one-off costs. The supplier pays a toolmaker before a single cable is built, and that cash leaves the supplier’s account months before any revenue arrives. Charging it separately is the straightforward way to recover it, and it keeps the unit price clean so the buyer can compare it against other quotations.
The alternative is to fold the cost into unit price against a committed volume. This is genuinely attractive when a program has a firm forecast: no upfront cash, a predictable piece price, and no separate approval needed for a capital item. It becomes a problem when the forecast does not materialize, because the unit price was calculated against volume that never came, and the supplier has recovered only part of what was spent.
- Upfront charge. Cleanest unit price, full ownership clarity, buyer carries the risk of program cancellation.
- Amortized into unit price. No upfront cash, piece price carries a hidden tooling component, supplier carries the volume risk.
- Partial upfront with a rebate. A middle path where part is paid at tool start and part is credited back as volume accumulates.
How Amortization Actually Works
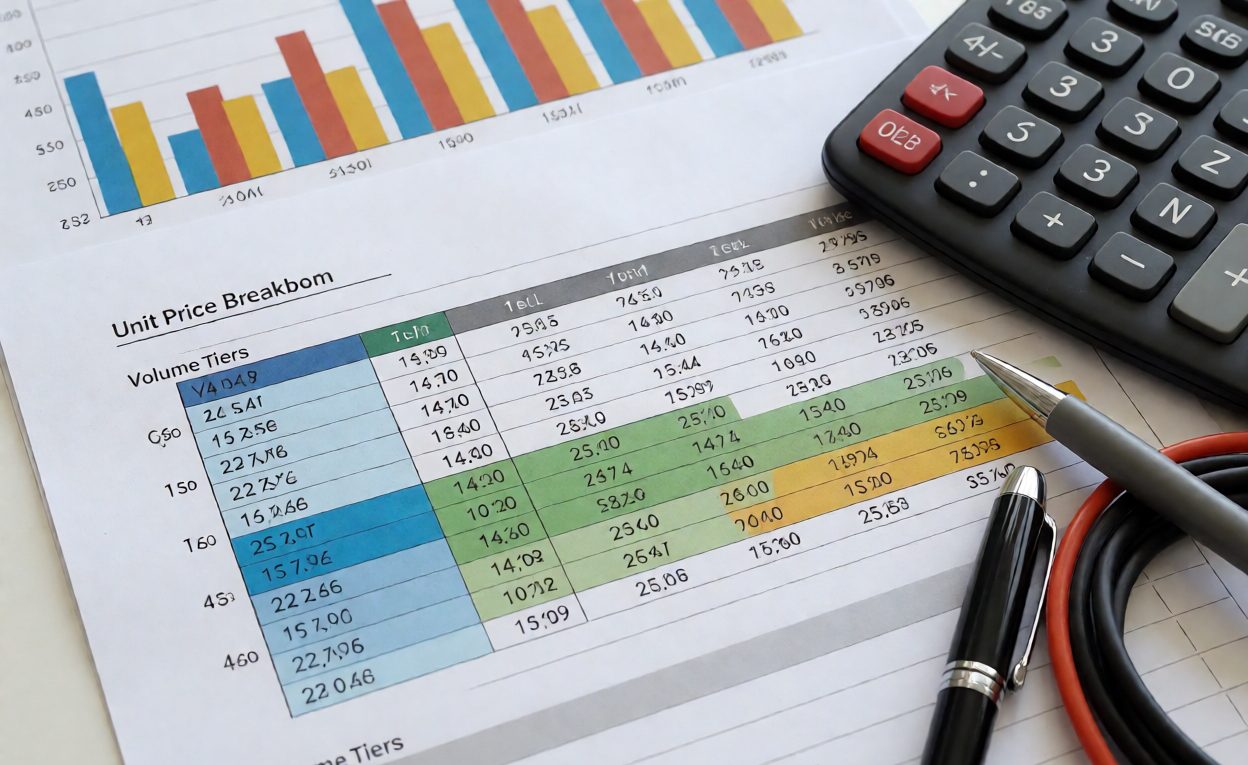
Amortization in this context is simple arithmetic. Take the tool cost, divide it by the committed quantity, and add the result to each unit. If a tool costs eight thousand dollars and the commitment is twenty thousand pieces, each piece carries forty cents. If the program only ever buys five thousand pieces, the supplier has recovered two thousand of the eight.
That gap is why amortized tooling always comes with a commitment, and why the commitment needs to be written as a number with a date. “Against ongoing volume” is not a commitment. “Twenty thousand pieces within eighteen months of first article” is, and it gives both sides something to measure against. Where the buyer cannot commit to a number, the honest answer is usually an upfront charge, because the risk has to sit somewhere.
Two details are worth checking in any amortized quote. First, whether the tooling component is identified separately on the quotation even when it is not invoiced separately, so the buyer can see what piece price would be once the tool is paid off. Second, what happens after the committed volume is reached: a well-written quote drops the tooling component rather than continuing to collect it silently.
Refund, Rebate and Credit Terms Compared
The three words get used interchangeably and mean different things. A refund returns cash. A rebate returns value as a credit against future invoices. A credit reduces a specific future invoice, usually the next one. Suppliers strongly prefer credits, for the ordinary commercial reason that a credit keeps the revenue in the program, and buyers should be clear about which they are agreeing to because a credit is worthless if the program has ended.
Refund clauses also need a trigger and a cap. The common structure is a volume milestone: reach the committed quantity within the stated period and a defined portion of the tooling charge is rebated, in full or in steps. Some suppliers offer a full refund at milestone and some only a partial one, on the reasonable argument that a tool used for fifty thousand pieces has delivered most of its value regardless of who paid for it. Both positions are defensible; the point is that the number should be agreed before the tool is cut.
There is one clause buyers should watch for: a refund tied to exclusivity or to placing all future volume with that supplier. That is not a tooling term, it is a supply agreement wearing a tooling term’s clothing, and it should be evaluated as one.
Technical Background
The spreading of a one-off cost across production units is amortization, the same principle used for any prepaid asset. Tooling itself is normally treated as capital expenditure on the supplier’s books rather than as a consumable, which is why it appears as a separate line rather than being absorbed into overhead. The document that carries the terms is the purchase order, and a tooling clause written only in email is the one that gets argued about two years later.
Writing the Terms So Nobody Argues Later
- Name the tool and the part number it serves. A tooling charge tied to a part number is auditable; one tied to a project name is not.
- State ownership. Supplier-owned, buyer-owned or buyer-owned with supplier custody, and what custody includes.
- State the commitment as a number and a date. Quantity and period, both measurable.
- Define the remedy in the right currency. Cash refund, invoice credit or unit price reduction, with a cap and a trigger.
- Cover the early exit. What happens on cancellation before first article, after first article, and after production starts.
- Cover maintenance and life. Who pays for refurbishment, and what happens when the tool reaches end of life mid-program.
Buyers who get these six lines into the purchase order rarely end up discussing tooling again. Buyers who leave them out discover, usually at the moment they want to move the program to another supplier, that a tool paid for but never owned is difficult to collect.
One-off charges beyond tooling are described in NRE and sample cost policy, and the wider price structure in cable quotation cost drivers. Where a tool is a mold, the design decisions driving its price are set out in overmold design and tooling cost, and the longer view on paying for tooling appears in total cost of ownership for cable assemblies. Volume commitments interact with MOQ and lead time expectations as well.
Frequently Asked Questions
What does tooling amortization mean on a cable quote?
The one-off tool cost is divided across a committed quantity and added to each unit price instead of being invoiced upfront.
Is it better to pay for tooling upfront or in unit price?
Upfront if volume is uncertain; amortized if a firm quantity commitment can be made and no upfront capital is wanted.
Who owns the tool after I pay for it?
Whatever the purchase order says. Ownership must be stated explicitly, including who holds and maintains the tool.
What is the difference between a refund and a credit?
A refund returns cash; a credit reduces a future invoice, which is worthless if the program has already ended.
What happens if the program is cancelled early?
That is the clause to negotiate before the tool is cut: define the remedy at each stage from engineering through production.
Should the tooling component disappear after the commitment is met?
Yes. A well-written quotation removes it at milestone rather than continuing to collect it silently.
Can I take the tool to another supplier?
Only if the terms say the buyer owns it and cover release. Without that clause, custody usually stays with the builder.